All Categories
Featured

Life Insurance Options for United States Veterans
Table of Contents
1 Rates are based on the typical monthly premium for Georgia Direct Premium rates market Class A; Aflac Term Life Insurance TERM LIFE POLICY - Series 860000; Premiums might differ by coverage type, account, state of concern, and the election of additional/optional benefits. Material within this article is provided for general educational purposes and is not provided as tax, legal, health, or financial advice for any individual or for any particular circumstance. For complete information, including availability and expenses of Aflac insurance coverage, please contact your local Aflac agent/producer.
In Delaware, Policies A68200, A68300 & A68400. In New York, Policies NY68200, NY68300 and NY68400. Whole Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368100. In Delaware, Policy A68100. In New York City, Policy NYR68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400.
Comprehensive Life Insurance Options for Veterans
In Delaware, Policies B61JWO & B61JTO. Q60000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Pennsylvania & Texas, Policy ICC18Q60200M.

Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK.
Policies and riders may likewise include a waiting period. Refer to the specific policy and rider kinds for benefit information, definitions, constraints and exclusions. Premiums are guaranteed by CMFG Life Insurance Coverage Company.
How to Get Cheap Family Health Insurance in 2026
If you're one of them and you delay buying life insurance till you have children, it might cost you the chance of locking in a low premium. Even if you don't yet have kids to secure, life insurance can cover your personal financial obligations, medical costs, home mortgage, lost incomes, and even funeral costs. Your health status is one of the most crucial elements when figuring out term life insurance rates.
Insurance in Oceanside CAThe much healthier you are, the less you pay, so getting life insurance coverage at a younger age can be useful. As you age, the danger of developing health concerns(such as cancer or diabetes)boost, and can lead to higher premiums and in some cases even make it hard to get protection. Here is a complete rate breakdown demonstrating how premiums increase decade by years.
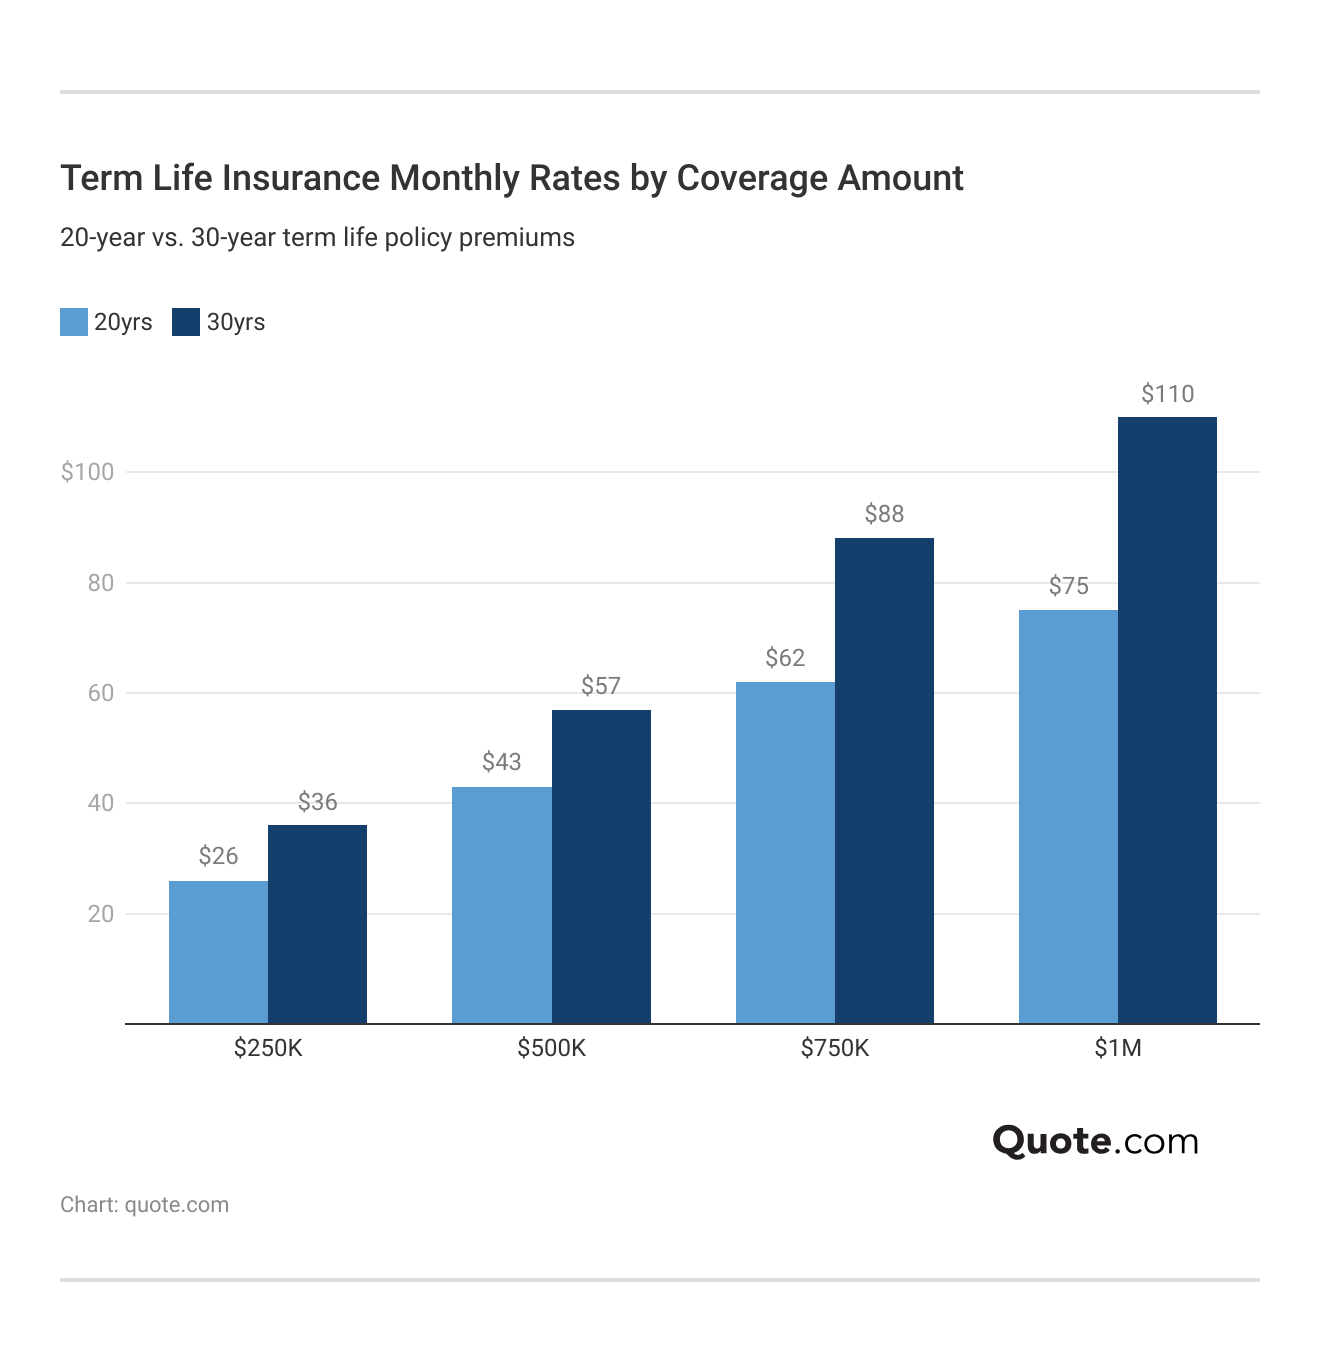
AgeMonthly PremiumAnnual CostTotal Over 20 Years25$18$216 $4,32030 $21$252 $5,04035$26 $312$6,24040$36$432$8,64045$55$660$13,20050$85$1,020$20,40055$135$1,620$32,40060$215$2,580$51,600 AgeMonthly PremiumAnnual Cost25 $15$18030$ 18$21635$22$26440$30$36045$45$54050$68$81655$108$1,29660$175$2,100 Rates are quotes. Real premiums depend on health, carrier, and state. The distinction in between buying at 30 vs. 50 is $64/month or $15,360 over 20 years for the very same coverage.
Here is a 20-year level term rate chart across $250K, $500K, and $1M (male, Preferred Non-Smoker): Age$250,000$500,000$1,000,00030$14$21$3840$23$36$6550$52$85$15660$128$215$395 Doubling your coverage does double your premium a set policy charge is spread across more coverage, so $1M is usually far less than 2 the $250K rate. If you are choosing between quantities, buying more protection while young is frequently the better value.
Cigarette smokers generally pay the non-smoker premium at the very same age. A lot of providers move you to non-smoker rates after tobacco-free, so stopping before you apply can cut your premium roughly in half.

Latest Posts
Understanding How Whole Life Insurance Builds Value for Wealth

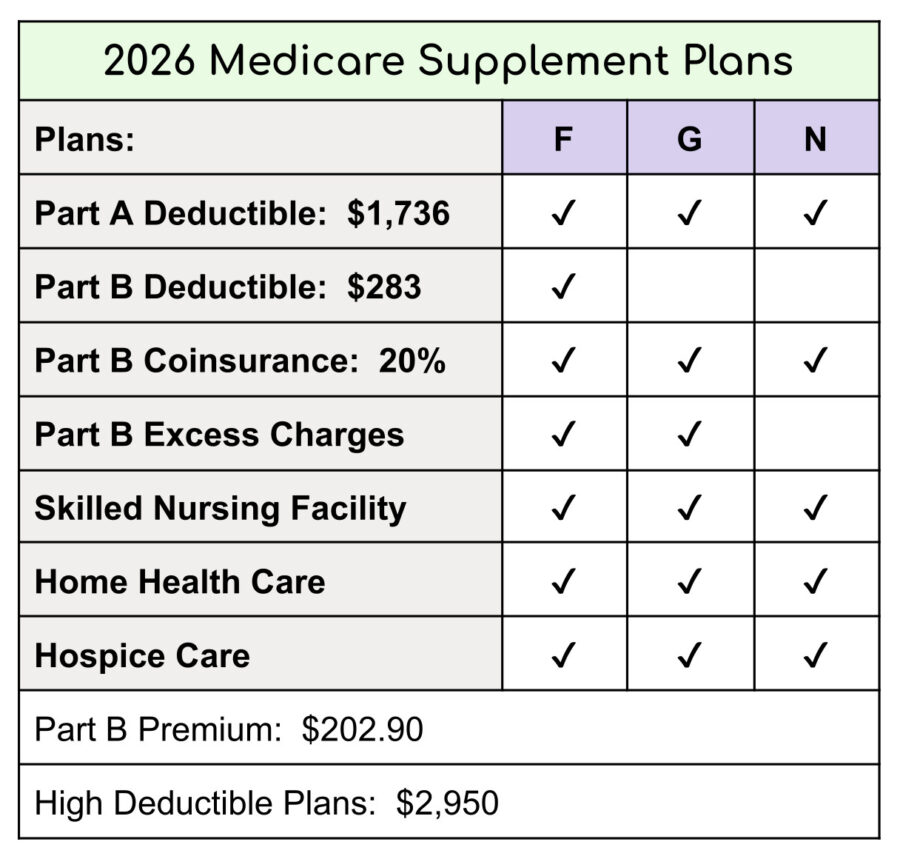
2026 Supplement vs Medigap Options
Finding Final Expense Insurance Coverage